Book a Consultation
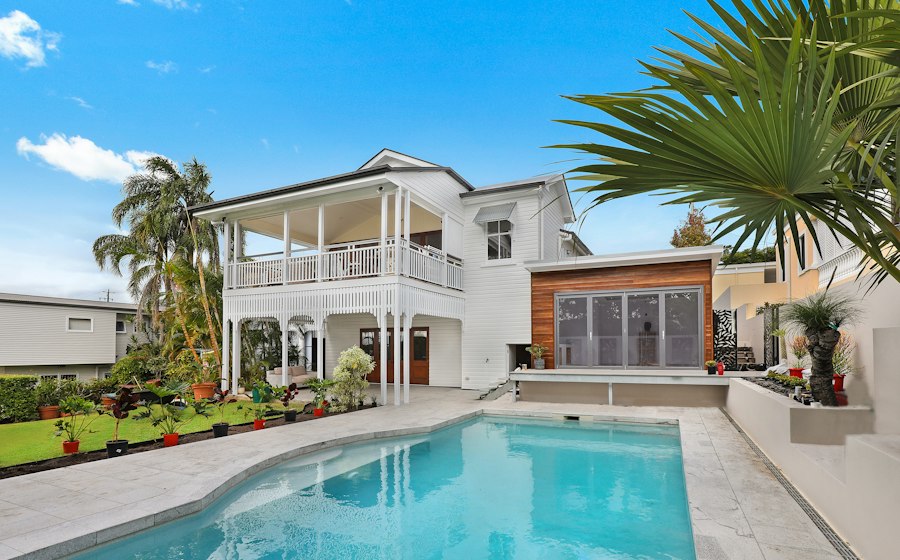
A weatherboard home behind a picket fence, the kind of first home a paramedic buys

Your roster doesn't fit the form.

Ambulance income is awkward on paper. A base wage that understates what you actually earn, overtime that moves by period, on-call that comes and goes, and salary packaging that some lenders handle well and others barely understand.

Put that into a bank's online calculator and the number you get back bears no relation to what you really earn. Most ambos who have wondered about buying stopped there.

I spent ten years inside a bank built for this community, where an ambulance payslip was a normal Tuesday rather than an exception.
Find out what you can borrow

There isn't one door into a first home.
There are several.

Most ambos we speak to are measuring themselves against twenty per cent saved. It is the wrong test, and on a paramedic's income it is usually also the slowest route in.

01

A government scheme

The First Home Guarantee gets eligible first home buyers in with a far smaller deposit and no LMI, and for most paramedics this is the route that actually applies. The First Home Owner Grant and Victoria's stamp duty concessions are separate again, with rules of their own.

02

A five per cent deposit

Where a scheme does not fit, lenders will still lend against a five per cent deposit in the ordinary way, with LMI payable. How much you can borrow on that deposit is where salary packaging starts to matter, and where lenders stop agreeing with each other.

03

An occupation-based LMI waiver

A handful of lenders extend professional policies beyond the medical list, and ambulance roles sometimes sit inside them. It is not something to count on, and it is equally not something to assume you have been shut out of.

Your packaging, your overtime and your on-call all change which of these leaves you best off. Working that out costs nothing and takes one conversation.

Three things worth knowing
before you decide you can't

Payslips and paperwork on a desk, the shift income a lender assesses

Overtime and on-call both count

How much of each depends on the lender. Consistent overtime is usually assessable; on-call allowances vary far more widely, and knowing which lender treats them generously is most of the job.

Keys to a first home, bought with a smaller deposit than most buyers assume they need

Your salary packaging matters

As a health service employee you may be able to package a meaningful part of your income. Lenders treat packaged income very differently, and the gap between the best and worst read is substantial.

An Australian home, the kind of first purchase planned months before the search begins

Timing changes the number

The decisions that move your borrowing capacity happen before you find a property. Clearing a debt, how you hold your savings, and when you apply all matter more than people expect.

Packaged income, read
four different ways

Salary packaging is one of the biggest variables in an ambulance application, and one of the least consistently handled across the market.

What it can do for you

Packaging reduces taxable income, which is the point of it, and it can leave you better off month to month in a way a lender ought to recognise.

A lender that reads packaging properly may assess your capacity meaningfully higher than one that does not.

What it can cost you

Some lenders discount packaged income, treat it as unreliable, or disregard it. A novated lease sitting inside the package is a liability on top of that.

The same package can move borrowing capacity substantially in either direction, depending purely on where the application lands.

That gap is not visible from the outside, and it is the single biggest reason an ambulance application is worth putting in front of someone who has read hundreds of them.

Questions paramedics ask

The ones that come up most often when an ambo is buying a first home.

Both, depending on the lender. Handled well it can lift your assessed capacity. Handled poorly it is discounted or ignored, and a novated lease inside it counts against you.

The practical answer is that packaging makes lender selection matter more, not less.

More variably than overtime. Some lenders assess it where there is a consistent twelve-month pattern, others apply a heavy discount, and a few will not count it at all.

Where on-call is a real part of your income, it is worth choosing the lender around that rather than finding out afterwards.

Sometimes, and it is worth checking rather than assuming. The occupation-based waivers are clearest for nurses, midwives and doctors, and some lenders extend professional policies further than others.

Where a waiver is not available, the First Home Guarantee is usually the route that applies.

Yes, and usually by more than people expect. It is a liability as well as a packaging benefit, and the two are assessed separately.

If you are thinking about a lease and a home in the same year, the order you do them in matters.

Before. The decisions that cost people money happen in the months before they find somewhere, not in the week after.

Find out what you can actually borrow

A fifteen-minute conversation, worked around your roster. No obligation, and an honest answer either way.

Early, late or around your roster. See first home buying in general, or everything else we help with.