Book a Consultation
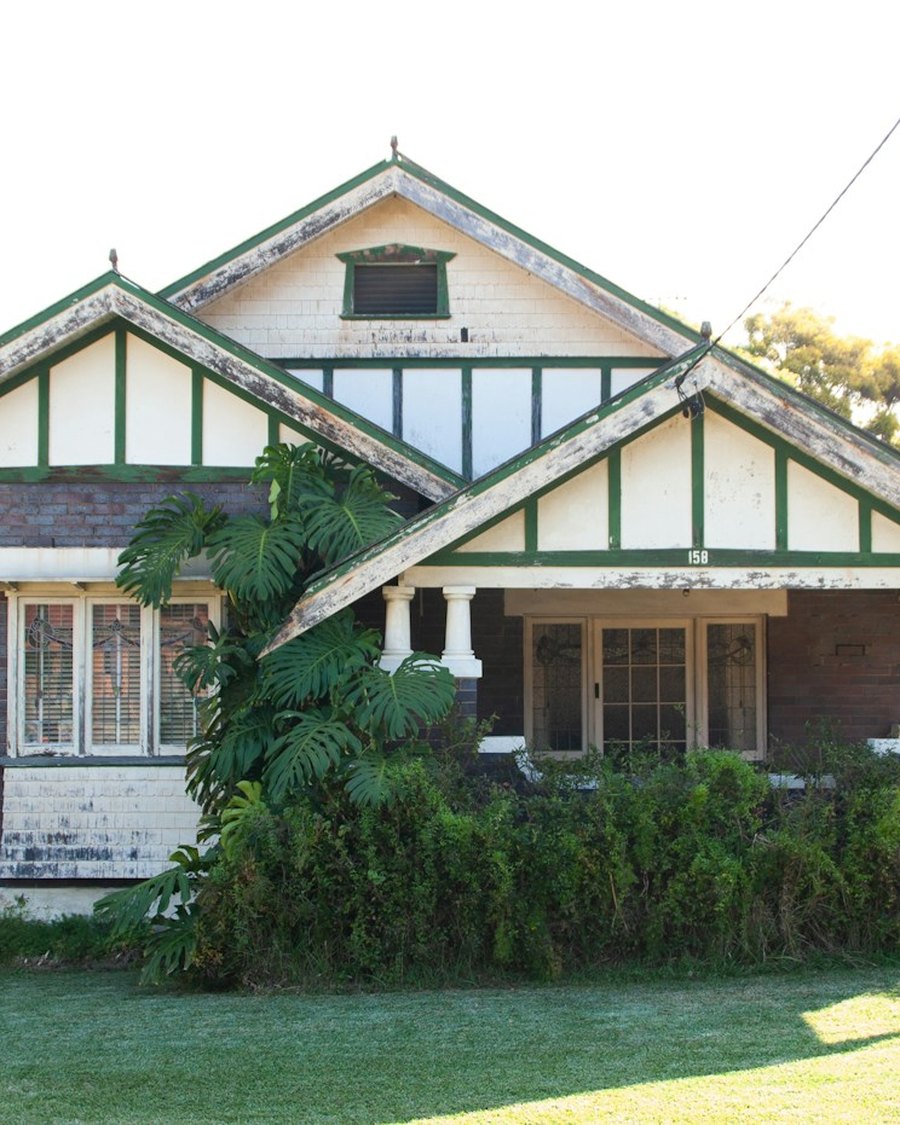
A Californian bungalow in Melbourne, the kind of first home a nurse or midwife buys

You may be the easiest yes in the building.

Lender LMI waivers are occupation-based, and they are most formalised for nurses, midwives and doctors. Where police and firefighters get a complicated answer, healthcare generally gets a clean one.

That can mean a meaningfully smaller deposit with no lenders mortgage insurance to pay, which is money that stays with you rather than insuring the bank. Most nurses we talk to have never been told it exists.

The other half of a nursing application is salary packaging, which every lender reads differently and which moves the number more than people expect.
Find out what you can borrow

There isn't one door into a first home.
There are several.

Healthcare workers get handed the same advice as everyone else: twenty per cent saved, or come back later. For a nurse or a midwife that advice is usually wrong, and often wrong by a wide margin.

01

An occupation-based LMI waiver

Lenders mortgage insurance is normally payable once you borrow above a set percentage of a property's value, and an occupation-based waiver removes it. For nursing and midwifery this is among the most formalised professional policies in the market, and it is the one most nurses have never been told about.

02

A five per cent deposit

If a waiver does not reach as far as you need it to, lenders will still lend against a five per cent deposit in the ordinary way, with LMI payable. Occasionally that is the better answer even where a waiver is available, and the only way to know is to run both.

03

A government scheme

The First Home Guarantee, the First Home Owner Grant and Victoria's stamp duty concessions sit outside lender policy altogether. A waiver does not rule them out, and now and then a scheme beats the waiver outright.

Two or three of these are usually open to a nurse at once, and they do not all point the same way. Working out which combination leaves you best off takes one conversation.

Three things worth knowing
before you assume you cannot

Keys to a first home, bought with a smaller deposit than most buyers assume they need

The LMI waiver is usually a clean yes

Nurses, midwives and doctors can often borrow a higher percentage of a property's value without paying lenders mortgage insurance. That is money that stays with you rather than insuring the lender.

Payslips and paperwork on a desk, the shift income a lender assesses

Packaging is read differently by every lender

Healthcare salary packaging is substantial and handled inconsistently. Some lenders assess it properly, some discount it heavily, and the gap between them is worth real borrowing capacity.

An Australian home, the kind of first purchase planned months before the search begins

Agency and bank shifts can count

Irregular shifts are not automatically discounted. Where there is a consistent pattern over a reasonable period a number of lenders will assess them, though which ones and at what rate varies.

What a waiver is
actually worth

This is the single biggest advantage available to healthcare workers buying a first home, and it is routinely left on the table.

What it is

Lenders mortgage insurance protects the lender rather than you, and it is normally payable once you borrow above a set percentage of a property's value.

An occupation-based waiver removes it. For nurses and midwives this is one of the most formalised professional policies in the market.

What it is not

It is not universal. Each lender sets its own list of eligible occupations, its own maximum, and its own conditions.

It is also separate to the First Home Guarantee. Depending on your circumstances one may suit you better than the other, and occasionally neither is the right answer.

Working out which lender's waiver you qualify for, and whether it beats the alternative, is a short conversation with a large number attached to it.

Questions nurses and midwives ask

The ones that come up most often when a healthcare worker is buying a first home.

No. Each lender keeps its own list of eligible occupations, its own maximum borrowing percentage and its own conditions, and they are not the same.

Finding the one whose policy fits your role and your deposit is the work, and it is worth doing before you apply anywhere.

Less than twenty per cent in most cases, and sometimes considerably less. The exact figure depends on which lender's waiver applies to you and what you are buying.

We would rather work that out with your real numbers than quote a percentage that may not be the one you get.

Inconsistently, which is the problem. Some lenders assess packaged income properly, some apply a discount, and a few largely disregard it.

Where packaging is a meaningful part of your income, choosing the lender around it is worth real borrowing capacity.

Often, where there is a consistent pattern over a reasonable period. Lenders differ on how long that period needs to be and how much of the income they will count.

If a good share of your income comes from agency or bank work, that should shape which lender you approach.

Sometimes, and sometimes not. A waiver is a lender policy and the Guarantee is a government scheme, with different eligibility, different limits and different trade-offs.

They are worth comparing properly rather than assuming the waiver wins because it is the one you qualify for.

Find out what you can actually borrow

A fifteen-minute conversation, worked around your shifts. No obligation, and an honest answer either way.

Early, late or around your shifts. See first home buying in general, or everything else we help with.