Book a Consultation
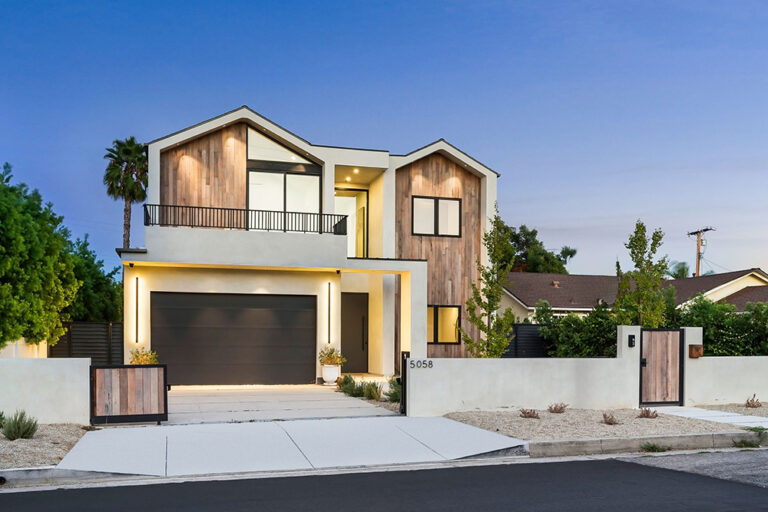
A modern two-storey Melbourne home at dusk, the kind bought as a second or third move

Loyalty and suitability are not the same thing.

Most people we sit down with have been with the same bank since the day they joined. It is what everyone at the station did, nobody has ever had a bad word to say about it, and nothing since has forced the issue.

That bank has two sets of customers. The ones it is trying to win, and the ones it already has. The sharpest pricing goes to the first group. You have been in the second group for years.

Sometimes that gap is worth moving for and sometimes it is not. We will work out which, and if the answer is that you are better off where you are, that is what we will tell you.
See where you stand

Three things worth checking
before you renew by default

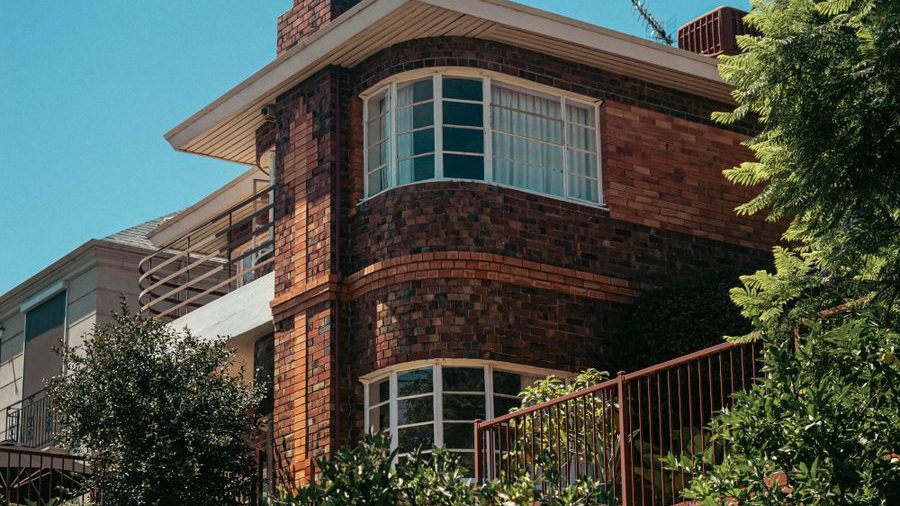
A established brick home of the kind bought a decade ago and since paid down

What your place is worth now

Most people are working off the number they paid, or a figure a neighbour mentioned. If you bought more than a few years ago, the equity sitting in the property is usually the thing that makes the next move possible.

Signing a loan document

The front book and the back book

New customers and existing customers are rarely offered the same thing. Add an annual package fee for features you have never used, and the cost of staying put quietly compounds.

A couple going through their loan paperwork at the kitchen table

Whether moving is worth it

Switching takes paperwork and a few weeks. It is not always worth it. We run the comparison including the costs of moving, and if it does not leave you in front, we say so.

The question is rarely the rate.
It is usually the order.

Upgrading, buying an investment and refinancing all draw on the same equity. What separates a clean move from an expensive one is almost always the sequence.

Buying before selling

The most common question we get is whether two loans can be carried at once, even briefly. The answer depends on how your income is assessed and what the existing loan looks like, not on a general rule.

Done in the right order it is routine. Done in the wrong order it can mean accepting the first offer on a property you were not ready to sell.

Restructuring while you are there

A refinance is the natural moment to fix things that were set up years ago and never revisited: an offset that was never used, a split that no longer matches how you are paid, a term that has quietly reset.

Doing that at the same time costs nothing extra. Doing it later usually means another application.

If you are thinking about a move in the next year or two, the conversation is worth having now rather than once a property has caught your eye. The options are wider while nothing is urgent.

Refinancing and upgrading questions

The ones that come up most when people are weighing up a move.

An application is recorded, and several applications in a short period can be read poorly by a lender. One well-prepared application put to a lender whose policy suits you is a very different thing to five speculative ones.

That is part of why we work out where an application should go before it is lodged rather than after.

Then we will tell you that. It happens reasonably often, particularly where a loan is already well priced or where exit and establishment costs outweigh the saving.

Occasionally the useful outcome is that we go back to your existing lender and ask them to reprice, which is a conversation they take more seriously when there is an alternative on the table.

Often, yes. Releasing equity is a common way to fund a deposit on the next place, a renovation, or an investment purchase, and it is assessed on your position and the purpose at the time.

What you can release, and whether it is sensible to, depends on the numbers. It is worth modelling before it is needed.

It changes how your income is read rather than making it harder. Overtime, penalties and allowances are treated differently by different lenders, and the same payslips can produce materially different borrowing figures.

That variation works in your favour once you know where to put the application.

Find out where you actually stand

A short conversation, worked around your roster. An honest answer either way, including if that answer is to leave things as they are.

Early, late or around your roster. See everything else we help with, or read how the process works.